
Table of Contents
- What Is Articulated Truck Financing
- Types of Articulated Haulers and Equipment You Can Finance
- Heavy Equipment Loans for Owner-Operators
- How to Qualify for Articulated Truck Financing
- Auction Financing Pre-Approvals and Used Equipment
- Financing for Older Equipment and No Age Restrictions
- Commercial Truck Financing for Contracting Businesses
- Total Cost of Ownership and Machine Uptime
- Frequently Asked Questions
Last Updated: September 25, 2026
What Is Articulated Truck Financing
Articulated truck financing is the process of securing capital to purchase heavy-duty articulated haulers and equipment used in construction, mining, and hauling operations. An articulated truck, also called an articulated hauler, consists of a tractor unit connected to a separate cargo-carrying trailer via a pivot joint, allowing the vehicle to navigate tight spaces and uneven terrain. This financing approach enables contractors, owner-operators, and construction companies to acquire the machinery they need without depleting working capital.
Unlike traditional vehicle loans, articulated truck financing is structured specifically for commercial equipment. Lenders evaluate the equipment’s value, the borrower’s business history, and projected revenue generation. The process accounts for the fact that heavy equipment depreciates differently than standard vehicles and often serves as collateral for the loan itself.
At Always Capital, we understand that acquiring articulated haulers represents a significant capital expenditure for any business. Our approach to articulated truck financing focuses on speed and accessibility, recognizing that downtime costs money. We work with all credit types and can move approvals in as little as two to four hours, ensuring your operation doesn’t stall while waiting for funding.
Types of Articulated Haulers and Equipment You Can Finance
Off-Road Dump Trucks and Heavy Haul Vehicles
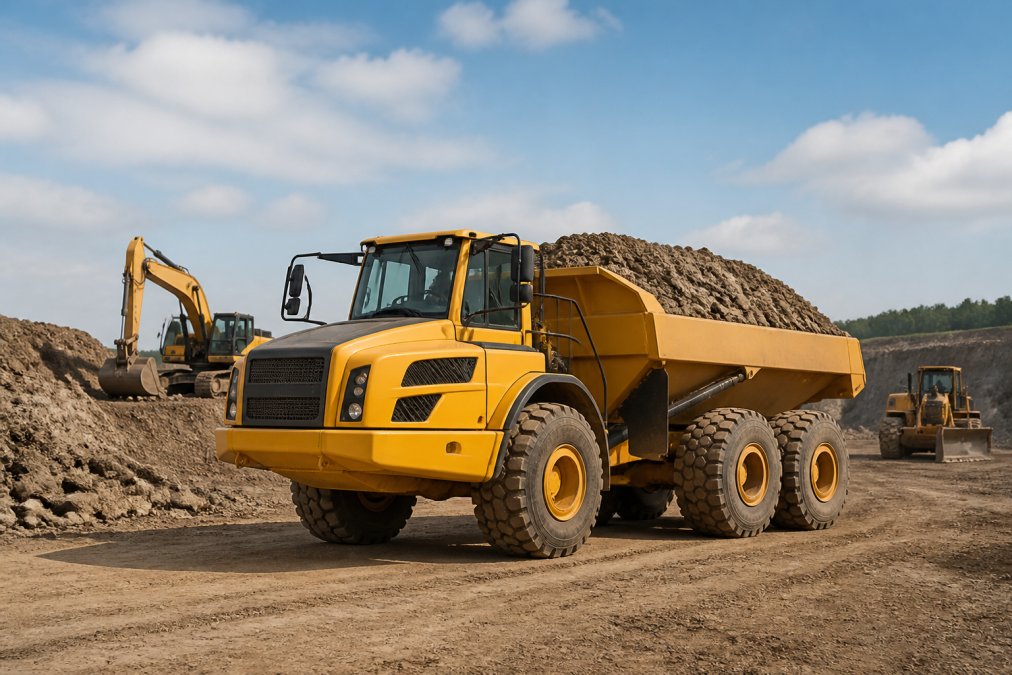
Off-road dump trucks and articulated haulers designed for heavy haul operations represent the most common equipment financed through commercial truck financing programs. These vehicles handle demanding conditions, rocky terrain, steep grades, muddy sites, where standard trucks would fail. Off-road models feature reinforced suspensions, specialized tires, and higher ground clearance than on-road equivalents.
Heavy haul vehicles often include rigid-frame dump trucks, articulated dump trucks (ADTs), and specialized haulers used in mining and quarry operations. These machines typically cost significantly more than standard commercial trucks, making financing essential for most businesses. The equipment’s durability and resale value make it attractive collateral for lenders evaluating loan applications.
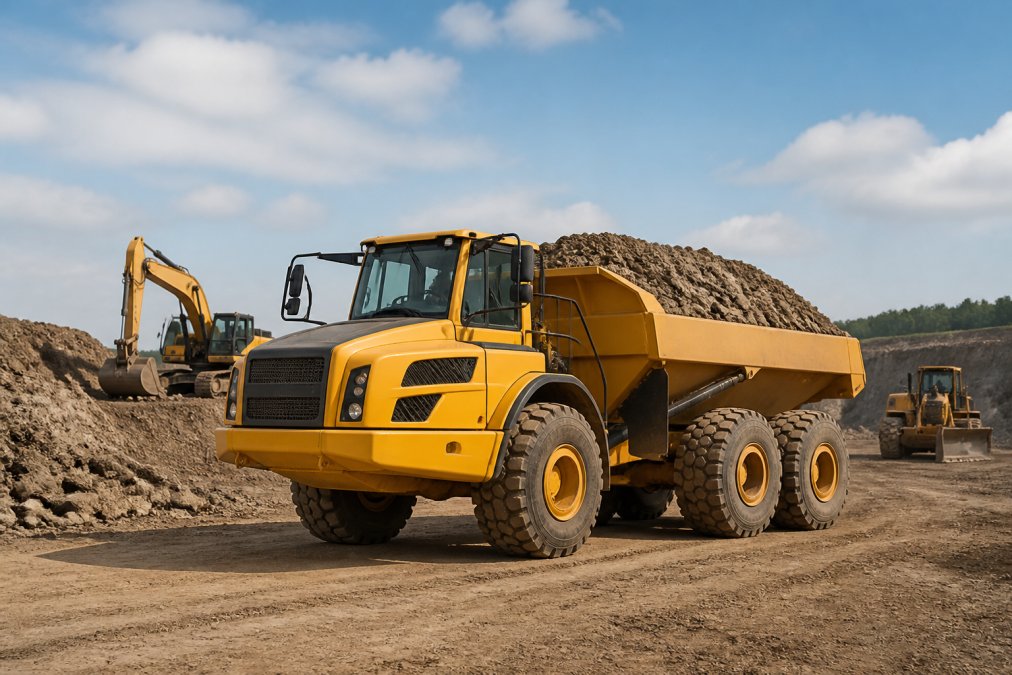
When financing off-road equipment, lenders consider the specific use case. A dump truck used for aggregate hauling has different value and depreciation patterns than one used for demolition debris. Equipment designed for specialized applications, like paver haulers or compactor transporters, may require lenders with specific expertise in those niches.
New vs. Used Equipment Options
The choice between new and used equipment fundamentally affects financing strategy. New articulated haulers come with manufacturer warranties, predictable maintenance costs, and the latest safety features. However, they carry higher purchase prices and steeper initial depreciation. Used equipment costs less upfront but may require near-term repairs, and warranty coverage is limited or absent.
Many contractors find that used equipment, particularly machines 3-5 years old, offers the best balance of cost and reliability. These vehicles have completed their steepest depreciation curve, yet they retain significant useful life. Financing used equipment often requires more detailed equipment appraisal, as lenders must verify actual condition rather than relying on manufacturer specifications.
Always Capital finances both new and used articulated truck options. For used equipment, we conduct thorough appraisals to ensure the asset supports the loan amount. This approach protects both the lender and the borrower by preventing over-using on depreciating assets.
The financing terms may differ slightly between new and used purchases. New equipment typically qualifies for longer loan terms (up to 84 months) because depreciation is more predictable. Used equipment financing often features shorter terms (36-60 months) to account for higher maintenance risk and faster value decline.
Find Out How Much You Can Borrow for Your Business Today! →
Heavy Equipment Loans for Owner-Operators
Owner-operators face unique financing challenges. Unlike established contracting firms with multiple years of financial history, owner-operators often operate with minimal overhead and inconsistent revenue documentation. Traditional lenders view this as higher risk, requiring larger down payments or rejecting applications outright.
Heavy equipment loans designed for owner-operators acknowledge this reality. These loans prioritize the equipment’s value and the operator’s ability to generate revenue with that equipment, rather than demanding extensive corporate financial statements. Lenders evaluate the specific hauling contracts or work opportunities the owner-operator has secured.
For owner-operators seeking articulated truck financing, the path forward requires demonstrating viable work. Signed contracts, letters of intent from major clients, or established relationships with construction firms all strengthen applications. Some owner-operators secure pre-approvals before purchasing, giving them negotiating power with equipment dealers.
Always Capital has built its reputation partly on serving owner-operators who were rejected elsewhere. Our soft credit pull process means a preliminary application doesn’t damage credit scores, allowing operators to explore options without risk. We accept applications from operators with challenging credit histories, understanding that past financial difficulties don’t predict future performance with the right equipment.
How to Qualify for Articulated Truck Financing
Credit Approval and Soft Pull Process
Qualifying for articulated truck financing starts with a credit evaluation, but the process doesn’t require the hard credit inquiries that damage credit scores. A soft pull, also called a soft inquiry, reviews creditworthiness without creating a record visible to other lenders. This distinction matters significantly for owner-operators and small business owners who may be exploring multiple financing options.
The soft pull process examines credit history, existing debt obligations, and payment patterns. Lenders look for evidence that the borrower manages obligations responsibly, even if past difficulties exist. A single late payment five years ago doesn’t disqualify applicants; patterns of chronic delinquency carry more weight.
All credit types are accepted in modern equipment financing. Borrowers with excellent credit, fair credit, or challenged credit can all qualify. The difference typically appears in loan terms rather than outright rejection. A borrower with excellent credit might receive 84-month terms at favorable conditions, while a borrower rebuilding credit might receive 60-month terms with slightly adjusted parameters.
Documentation and Application Requirements
The documentation required for articulated truck financing varies based on loan amount and borrower profile. For smaller loans or pre-approvals, lenders may require minimal documentation, sometimes just a completed application form. For larger loans, additional documentation typically includes bank statements and details about existing debt.
Always Capital offers application-only approvals up to $500,000 for qualifying borrowers. This means no financial statements or extensive documentation are required to receive approval. The application itself provides sufficient information for the lender to assess risk and approve capital.
For loans exceeding $500,000, documentation requirements increase. Typical items include recent bank statements (usually 90 days), details about existing equipment and vehicles, and information about the specific purchase planned. This documentation helps lenders verify that the business generates sufficient revenue to support the loan payments.
The application process itself is straightforward. Applicants provide basic business information, details about the equipment being financed, and authorization for a soft credit pull. The entire process typically takes less than an hour to complete.
Find Out How Much You Can Borrow for Your Business Today! →
Auction Financing Pre-Approvals and Used Equipment
Purchasing equipment at auction presents both opportunities and challenges. Auctions offer competitive pricing and access to equipment that might not be available through traditional dealers. However, auction purchases require immediate payment, and financing arrangements must be in place beforehand.
Auction financing pre-approvals solve this timing problem. Borrowers receive pre-approval for a specific loan amount before attending an auction.
Financing for Older Equipment and No Age Restrictions
Traditional lenders often impose age restrictions on financed equipment. A lender might refuse to finance vehicles older than 10 years, regardless of condition or value. This restriction creates a barrier for contractors who operate well-maintained older equipment or who find exceptional values in slightly aged machines.
Commercial Truck Financing for Contracting Businesses
Contracting businesses often need multiple pieces of equipment operating simultaneously. A grading company might require articulated haulers, dozers, and support vehicles. A paving operation needs dump trucks, compactors, and specialized haulers. Financing these fleets requires a different approach than financing a single piece of equipment.
Flexible Payment Terms and Deferred Payments
Flexible payment terms represent a key advantage of modern articulated truck financing. Rather than rigid 60-month schedules, borrowers can negotiate terms ranging from 24 to 84 months depending on equipment type, purchase price, and business circumstances.
Total Cost of Ownership and Machine Uptime
Evaluating equipment financing requires looking beyond the loan payment itself. The total cost of ownership includes purchase price, financing costs, maintenance, repairs, insurance, fuel, and operator time. A slightly more expensive machine with lower maintenance costs might deliver better value than a cheaper alternative requiring frequent repairs.
Frequently Asked Questions
What documents are required for articulated truck financing?
Most lenders request proof of business ownership, identification, and basic financial information. Always Capital accepts application-only approvals up to $500,000 with no financials required, making the process faster for qualified buyers. For larger amounts or additional working capital, you may provide bank statements or tax returns, but many businesses qualify without them. The soft pull process means your credit won’t be harmed by the application itself.
Can I get financing for older articulated trucks?
Yes. Always Capital offers financing for older equipment and trucks with no age or mileage restrictions. Whether you’re purchasing a used articulated hauler from an auction, a dealer, or private sale, you can qualify for funding. Auction financing pre-approvals let you bid with confidence, knowing capital is ready when you win. This flexibility opens access to reliable used equipment that fits your budget.
How quickly can I get approved for heavy equipment financing?
Always Capital approves applications in as little as 2 to 4 hours. This speed means you can move fast when the right equipment becomes available, whether at auction or from a dealer. Same-day approvals let you secure equipment without losing time to lengthy underwriting. The soft credit pull process accelerates approval without damaging your credit score.
Is it possible to finance 100% of an articulated truck purchase?
Always Capital offers 100% financing options for qualified buyers, meaning you can finance the full purchase price of your articulated truck or heavy equipment. Combined with deferred payment plans of 30, 60, or 90 days, you get flexibility in how and when you pay. This approach helps preserve working capital for operations, payroll, and other business needs while you get the equipment you need immediately.