
Table of Contents
- What to Evaluate Before a Heavy Equipment Purchase
- Heavy Equipment Loans: Understanding Your Financing Options
- Financing for Older Equipment and Pre-Owned Machinery
- Auction Financing Pre-Approvals for Heavy Equipment Purchase
- Documentation and Approval Process
- Common Mistakes to Avoid in Heavy Equipment Purchase
- Frequently Asked Questions
Last Updated: September 21, 2026
What to Evaluate Before a Heavy Equipment Purchase
Buying heavy equipment requires careful assessment before committing capital. The condition, age, and maintenance history of machinery directly impact performance, downtime, and long-term operational costs. Contractors and business owners who skip this evaluation phase often face unexpected repairs and safety issues.
Assessing Equipment Condition and Age
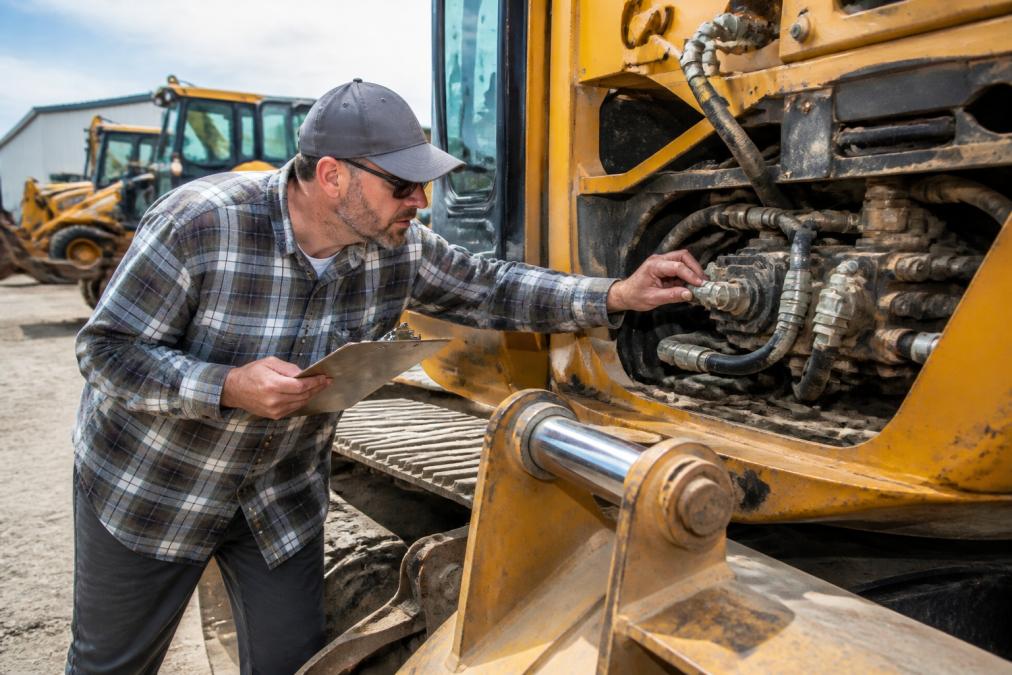
Equipment age matters, but condition matters more. A well-maintained 15-year-old excavator can outperform a neglected 3-year-old model. Examine the frame for cracks, corrosion, and structural integrity. Check hydraulic lines for leaks. Test all moving parts, boom articulation, bucket curl, track tension, to confirm smooth operation without grinding or hesitation.
Look for signs of heavy use: worn paint, dented panels, and oil stains indicate stress. Verify that all safety features work: emergency stops, warning lights, and backup alarms. Request a full walk-around inspection and take photos or video for your records. Always Capital supports customers purchasing equipment across all age ranges, with no age or mileage restrictions on financing.
Checking Maintenance History and Service Records
Request complete maintenance documentation. Regular service records prove the equipment has been cared for. Look for patterns: consistent oil changes, filter replacements, and component repairs indicate responsible ownership. Missing records or gaps in service history are red flags.
Ask the seller directly about major repairs, replacements, and any known issues. A transmission rebuild, new engine, or hydraulic system replacement affects both value and remaining service life. Cross-reference the seller’s claims with the equipment’s actual condition.
Heavy Equipment Loans: Understanding Your Financing Options
Heavy equipment financing works differently than standard business loans. Equipment serves as collateral, which means lenders assess the machinery’s value, condition, and resale potential. This asset-backed approach allows for more flexible terms and often faster approval than unsecured lending.
How Asset-Backed Loans Work
Asset-backed loans use the equipment itself as security. The lender evaluates the machinery’s fair market value, age, and condition to determine loan eligibility and amount. Because the equipment backs the loan, lenders can approve higher amounts and extend repayment terms beyond what traditional business loans offer.
The appraisal process determines fair market value. Professional appraisers assess equipment condition, comparable sales data, and depreciation. This valuation protects both borrower and lender. A bulldozer worth $80,000 might support a loan up to $80,000, depending on the lender’s loan-to-value ratio. Always Capital’s approach accepts all credit types and offers flexible terms, making equipment financing accessible even for businesses with challenged credit histories.
Flexible Repayment Terms and Down Payment Structures
Repayment flexibility distinguishes equipment financing from rigid business loans. Terms typically range from 24 to 84 months, allowing businesses to match payments with equipment-generated revenue. Shorter terms mean higher monthly payments. Longer terms reduce monthly burden but extend the financing period.
Down payment requirements vary. Some lenders require a down payment; others offer 100% financing options. Always Capital provides multiple structures, including deferred payment plans of 30, 60, or 90 days, giving businesses breathing room to integrate new equipment before payments begin. This flexibility helps contractors manage cash flow during equipment integration and training phases.
Financing for Older Equipment and Pre-Owned Machinery
Pre-owned and older equipment represents significant value for cost-conscious businesses. A used excavator costs a fraction of new equipment while delivering comparable performance if properly maintained. Financing older machinery requires lenders willing to assess condition rather than relying solely on age.
No Age or Mileage Restrictions
Equipment age shouldn’t prevent financing. A 20-year-old loader in excellent condition deserves financing just as much as a 5-year-old machine in poor condition. Always Capital finances equipment with no age or mileage restrictions, recognizing that condition and maintenance history matter more than calendar years.
This approach opens opportunities for budget-conscious contractors. Used equipment markets offer deep discounts on machinery that has decades of productive life remaining. Businesses can acquire multiple pieces of equipment for the cost of one new unit, expanding capacity without proportional capital expenditure.
Depreciation and Fair Market Value Assessment
Depreciation affects equipment value over time. Heavy machinery typically depreciates annually in early years, then stabilizes. Understanding depreciation helps buyers avoid overpaying for aging equipment.
Fair market value assessment protects buyers from overpaying and lenders from over-financing. Professional appraisals establish realistic values based on comparable sales, condition reports, and remaining service life. This valuation becomes critical when financing equipment from private sellers, where pricing lacks the transparency of dealer sales.
Auction Financing Pre-Approvals for Heavy Equipment Purchase
Auction environments move quickly. Pre-approval for heavy equipment purchase financing eliminates delays when the right equipment appears. Winning bids require immediate payment or deposit, and pre-approval ensures the capital is ready.
Why Pre-Approval Matters at Auction
Auction bidding demands speed. When equipment meets specifications and price is reasonable, hesitation means losing the opportunity. Pre-approval provides financing certainty before the gavel falls. Buyers can bid confidently, knowing funds are available.
Pre-approval also strengthens negotiating position. Auction houses and private sellers respect buyers with confirmed financing. Pre-approval demonstrates serious intent and financial capacity. Always Capital’s application-only approvals up to $500,000 and same-day approvals within 2-4 hours mean businesses can move quickly when opportunities arise.
Private Party vs. Dealer Purchase Considerations
Dealer purchases offer documented history, warranties, and established recourse if problems emerge. Private party sales typically cost less but require more due diligence. Private sellers may lack complete maintenance records or documentation of prior repairs.
Private party equipment requires thorough inspection before purchase. Buyers assume more risk but gain pricing advantages. Title verification becomes critical, confirm the seller owns the equipment free and clear, with no liens or claims. Lenders typically require clear title before financing, so resolve any title issues before seeking approval.
Documentation and Approval Process
Fast approval requires organized documentation. Lenders need clear information to make quick decisions. Preparing materials upfront accelerates the process from application to funding.
What You’ll Need to Gather
Prepare equipment details: make, model, year, serial number, and current condition description. Include photos from multiple angles showing overall condition and any visible wear. Gather the seller’s contact information and sale agreement or price quote.
For the business, compile basic information: business structure, years operating, and primary industry. Bank statements showing account activity and cash reserves help demonstrate financial stability. Tax returns or profit-and-loss statements provide income documentation. Always Capital’s application-only approvals up to $500,000 require minimal financials, simplifying the process for qualified applicants.
Fast Approval Timeline and Funding
Application-only approvals deliver decisions quickly. Always Capital processes applications in as little as 2-4 hours, allowing businesses to move fast when equipment opportunities arise. Once approved, funding typically follows within 24-48 hours, enabling purchase completion and equipment deployment.
Fast timelines matter in competitive markets. Equipment in demand sells quickly. Businesses with pre-approval or rapid-approval processes secure better selections and pricing. Slow financing processes mean missed opportunities and settling for less-optimal equipment.
Common Mistakes to Avoid in Heavy Equipment Purchase
Rushed decisions and incomplete due diligence create expensive problems. Avoiding common mistakes protects both purchase price and long-term equipment performance.
Skipping Inspection and Title Search
Skipping professional inspection is penny-wise, pound-foolish. A professional inspection can reveal significant hidden damage. Hydraulic leaks, transmission wear, and structural cracks don’t always show during casual observation. Third-party inspectors provide objective assessments and detailed reports documenting condition.
Title verification prevents legal complications. Confirm the seller owns the equipment outright with no outstanding liens. A lien holder can claim the equipment even after purchase, creating ownership disputes. Title searches prevent significant headaches.
Underestimating Maintenance and Repair Costs
Used equipment requires ongoing maintenance. Factor routine service, oil changes, filter replacements, hydraulic fluid, and wear-part replacement, into operating budgets. Older equipment may need more frequent service or component replacement.
Budget for unexpected repairs. Equipment failures create downtime that costs more than repair itself. A broken excavator sitting idle while awaiting parts can cost thousands in lost revenue. Reserve a portion of equipment value annually for maintenance and repairs, especially for older machinery.
Heavy equipment purchase decisions shape business capacity for years. Thorough evaluation, proper financing, and realistic maintenance planning separate successful acquisitions from costly mistakes. Always Capital supports businesses at every stage of equipment financing, offering flexible terms, fast approvals, and financing options for all credit types. Whether purchasing new, used, or auction equipment, working with experienced financing partners ensures the process moves smoothly and equipment deployment begins quickly. Apply now to get pre-approved for heavy equipment financing and move forward with confidence.
Frequently Asked Questions
What documentation do I need for a heavy equipment purchase?
You’ll need proof of business ownership, identification, and details about the equipment being purchased. For heavy equipment loans, most lenders request basic business information and equipment specifications. Always Capital offers application-only approvals up to $500,000 with minimal documentation requirements, making the process faster for qualifying businesses. The specific documents depend on your loan amount and creditworthiness.
How do I know if used equipment is worth financing?
Evaluate the equipment’s service life, maintenance history, and current market value. Older equipment can still be a solid investment if it has good maintenance records and realistic repair expectations. Always Capital finances equipment with no age or mileage restrictions, so even pre-owned machinery qualifies. Get a professional inspection to confirm condition before committing to purchase.
Why is pre-approval important before an equipment auction?
Pre-approval gives you a clear budget, speeds up bidding decisions, and prevents overspending in the heat of auction competition. Auction financing pre-approvals let you bid with confidence knowing your financing is already arranged. This is especially valuable at live auctions where quick decisions matter and funding delays can cost you the equipment.
Can I finance heavy equipment with challenged credit?
Yes. Always Capital works with all credit types and accepts all applications, recognizing that businesses face different financial situations. The company uses soft credit pulls that don’t hurt your credit score, and approval decisions focus on your equipment’s collateral value and business circumstances rather than credit history alone. Fast approvals within 2-4 hours mean you can move forward quickly.