
Table of Contents
- What Used Equipment Financing Companies Do
- Types of Equipment Eligible for Financing
- How the Equipment Financing Application Process Works
- Heavy Equipment Loans and Flexible Terms
- Financing for Older Equipment and Auction Financing Pre-Approvals
- Eligibility Requirements and Credit Considerations
- Key Benefits of Choosing the Right Financing Partner
- Frequently Asked Questions
Last Updated: September 23, 2026
What Used Equipment Financing Companies Do
Used equipment financing companies provide capital solutions that allow businesses to acquire machinery, trucks, and heavy equipment without depleting working capital.
Used equipment financing companies evaluate your business and equipment, then approve funding quickly, often within hours. Unlike traditional banks that focus heavily on credit history, they work with all credit types.
Always Capital exemplifies this approach by offering approvals in as little as two to four hours with soft credit pulls that don’t damage your credit score. The company finances all types of heavy equipment and commercial truck financing, accepting all applications and offering up to 100% financing for eligible equipment purchases.
The real value lies in speed and accessibility. When a business finds the right equipment at auction or private sale, waiting weeks for bank approval means losing the opportunity. Equipment financing removes that friction.
Types of Equipment Eligible for Financing
Used equipment financing companies fund a broad range of machinery essential to construction, landscaping, and industrial operations. Understanding what qualifies helps businesses plan their acquisition strategy effectively.
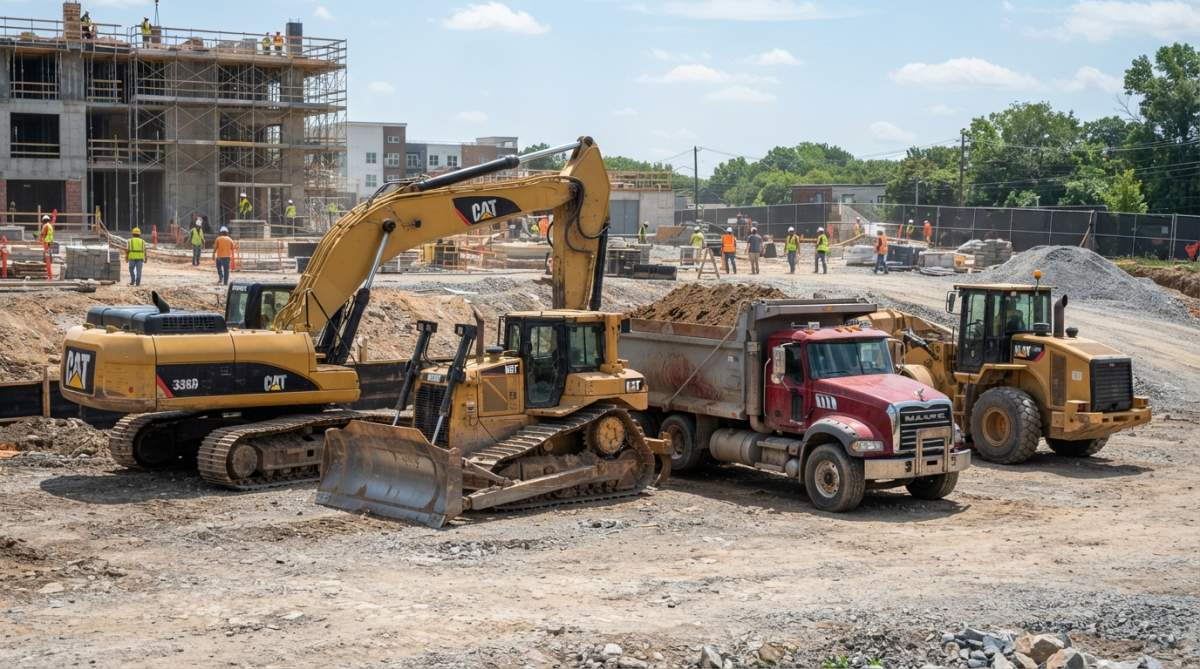
Heavy construction equipment represents the largest category. Excavators, backhoes, skid steers, loaders, dozers, and graders all qualify for financing through specialized lenders.
Commercial trucks and specialized vehicles are equally eligible. Dump trucks, daycab trucks, box trucks, and roll-off trucks can be financed through dedicated programs. Always Capital specifically supports excavator financing, backhoe financing, skid steer financing, loader financing, dozer financing, tractor financing, paver financing, and dump truck financing.
Many used equipment financing companies, including Always Capital, finance equipment with no age or mileage restrictions, opening doors for businesses seeking older, well-maintained machines or newer models.
Private party purchases, dealer sales, and auction acquisitions all qualify. The equipment itself serves as collateral.
How the Equipment Financing Application Process Works
Initial Application and Information Gathering
The first step involves providing basic business information: business name, structure, years in operation, owner contact, equipment description, and approximate purchase price. Many lenders, including Always Capital, accept applications with minimal upfront documentation in 15-30 minutes.
Equipment Details and Valuation
The lender requests equipment details (type, make, model, year, condition, purchase source, price) and conducts market valuation by checking comparable sales and assessing depreciation. This valuation determines the loan-to-value ratio and maximum advance amount.
Documentation Requirements by Loan Size
Documentation thresholds vary by lender. Always Capital’s approach: up to $500,000 requires application only; $500,000-$1 million requires basic business financials and proof of ownership; above $1 million requires full financial package. This tiered approach recognizes that smaller requests carry lower risk.
Credit Evaluation and Soft Pulls
Modern lenders use soft credit pulls instead of hard pulls. A soft pull assesses creditworthiness without appearing on credit reports or impacting credit scores, allowing businesses to apply with multiple lenders without credit damage. Always Capital uses soft pulls only.
Underwriting and Approval Decision
Underwriting evaluates debt service coverage ratio (DSCR), business stability, equipment collateral value, and payment history. Equipment lenders focus on equipment value and business revenue capacity rather than credit score alone.
Find Out How Much You Can Borrow for Your Business Today! →
Approval and Funding Timeline
Two-hour approvals are standard. Approval is communicated within 2 hours, loan documents are prepared within 24 hours, and funds are disbursed within 48 hours. For auction financing, pre-approval allows businesses to bid confidently knowing capital is secured.
Post-Approval: Documentation and Closing
Loan documents outline loan amount, payment schedule, equipment description, and default terms. Borrowers sign electronically or in person. The lender files a UCC-1 financing statement to establish security interest. Funding is released once documents are signed and filing is complete.
Equipment financing companies accept all credit types, focus on equipment value and business revenue, use soft credit pulls, complete underwriting in hours, and finance equipment with no age restrictions. This speed comes from specialization in machinery values, depreciation patterns, and industry cash flows.
Heavy Equipment Loans and Flexible Terms
Loan terms range from 24 to 84 months. Deferred payment options (30-90 days) allow businesses to acquire equipment immediately and delay payments until revenue flows. Fixed payments simplify budgeting. Always Capital offers 100% financing, meaning businesses acquire equipment without down payments or collateral beyond the equipment itself.
Financing for Older Equipment and Auction Financing Pre-Approvals
Conventional banks refuse to finance machines more than a few years old. Specialized lenders recognize that age doesn’t determine utility. Always Capital finances older equipment and trucks without age restrictions, opening possibilities for budget-conscious operators.
Auction financing pre-approvals allow businesses to bid confidently knowing funding is secured. Always Capital offers auction financing pre-approvals, enabling businesses to compete effectively without scrambling for last-minute financing. Inspection and appraisal ensure equipment justifies the financing amount.
Eligibility Requirements and Credit Considerations
Business Structure and Age
Business structure and age matter less than operational viability. Sole proprietorships, partnerships, LLCs, and corporations all qualify. Always Capital supports businesses under two years old with strong current revenue and clear operational plans, opening doors for entrepreneurs who would be declined by traditional banks.
Credit History and Credit Score Flexibility
Equipment financing companies accept all credit types. Poor credit, past challenges, limited history, and recent bankruptcy do not automatically disqualify applications. Lenders evaluate current payment patterns, revenue stability, equipment utilization, and industry patterns rather than credit scores alone.
Soft Credit Pulls Protect Credit Scores
Traditional lenders conduct hard inquiries, which appear on credit reports and temporarily lower credit scores by a few points. Multiple hard inquiries compound the damage. A business shopping with three banks might see a 10-15 point score reduction.
Soft credit pulls assess creditworthiness without appearing on credit reports or affecting credit scores, allowing businesses to apply with multiple lenders without consequences. Always Capital uses soft pulls only.
Documentation Requirements Simplified for Newer and Smaller Businesses
Modern equipment lenders have simplified documentation. Up to $500,000 requires application only with no financials. $500,000-$1 million requires one year of business financials plus proof of ownership. Above $1 million requires standard financial package. This enables newer, seasonal, and cash-based businesses to qualify without extensive documentation.
Debt Service Coverage Ratio (DSCR) as Primary Qualification Metric
The most important eligibility factor is debt service coverage ratio, the relationship between business income and loan obligations. A DSCR of 1.25 means the business generates $1.25 in revenue for every $1.00 in debt payments. This demonstrates financial stability and payment capacity.
For newer businesses, DSCR is calculated differently:
Find Out How Much You Can Borrow for Your Business Today! →
- Established businesses: Use historical revenue (last 12 months of P&L statements)
- Newer businesses: Use projected revenue based on contracts, customer commitments, or industry benchmarks. A business with signed contracts worth $200,000 over the next year can demonstrate DSCR based on those commitments, even without historical revenue.
This approach recognizes that a new business with solid customer commitments is lower-risk than an established business with declining revenue.
Industry and Equipment Type Considerations
Certain industries and equipment types have streamlined approval because lenders understand their cash flow patterns well:
- Construction and excavation: Predictable seasonal patterns, strong equipment demand, clear ROI on machinery
- Landscaping and grounds maintenance: Seasonal but reliable, strong spring-to-fall revenue
- Paving and asphalt: Seasonal, high equipment utilization, strong margins
- Trucking and hauling: Consistent demand, equipment-dependent revenue
Businesses in these sectors often qualify with less documentation than other industries because lenders have extensive data on their cash flows and equipment utilization patterns.
Personal Guarantees and Collateral
Most equipment financing requires the business owner to personally guarantee the loan. This means the owner is responsible if the business cannot pay. However, the equipment itself serves as primary collateral, the lender can repossess and sell the machine if payments are missed.
For 100% financing (where the loan covers the full equipment cost), the equipment is the only collateral required. Businesses don’t need to pledge personal assets, home equity, or other business equipment. This limits borrower risk while giving the lender a clear recovery path.
Why Newer and Smaller Businesses Qualify When Banks Say No
Equipment financing companies approve newer and smaller businesses that traditional banks reject because:
- Equipment is tangible collateral: Banks lend on cash flow and balance sheet strength. Equipment lenders lend on the machine itself. A startup with minimal balance sheet but a valuable piece of equipment can qualify.
- Specialization in equipment valuation: Equipment lenders have sophisticated systems for valuing used machinery. They know a 2018 Caterpillar 320 excavator is worth $85,000-$95,000 regardless of the buyer’s credit score. Banks don’t have this expertise.
- Industry expertise: Equipment lenders understand construction, landscaping, and trucking cash flows. They know a new paving company with signed contracts will generate revenue. Banks apply generic lending criteria.
- Risk is distributed: Equipment lenders fund hundreds of transactions monthly. A few defaults don’t threaten the business. Banks are more conservative because they have fewer transactions and higher loss sensitivity.
- Speed and efficiency: Equipment lenders have automated underwriting. They can approve in 2 hours because they’ve eliminated unnecessary steps. Banks require extensive review because they’re generalists.
Key Benefits of Choosing the Right Financing Partner
Selecting the appropriate used equipment financing company shapes the entire acquisition experience and long-term financial impact.
Frequently Asked Questions
How quickly can I get approved for used equipment financing?
Many used equipment financing companies offer rapid approval timelines. Some provide approvals within hours of application submission, with same-day funding available in certain cases. The speed depends on the completeness of your application and whether the financing company offers application-only approvals without requiring extensive financial documentation. Soft credit pulls, which don’t impact your credit score, also help accelerate the process.
Can I get financing for older heavy equipment or high-mileage trucks?
Yes, specialized used equipment financing companies work with pre-owned and older machinery. Many offer financing without age or mileage restrictions on trucks and equipment. This flexibility is valuable for businesses looking to expand their fleet affordably. Auction financing pre-approvals are also available, allowing you to bid confidently knowing financing is already arranged.
What types of equipment are eligible for used equipment financing?
Equipment financing covers a broad range of assets including excavators, backhoes, skid steers, loaders, dozers, tractors, pavers, dump trucks, daycabs, and box trucks. Heavy equipment loans extend to industrial machinery, commercial vehicles, and specialized construction equipment. Financing is available whether you’re purchasing from a dealer or a private party, and pre-approvals can be secured before you locate the specific equipment.
Do I need perfect credit to qualify for used equipment financing?
No. Used equipment financing companies work with all credit types, including businesses with challenged credit histories. The application process typically uses soft credit pulls, which don’t negatively impact your credit score. Many providers accept all applications and focus on your business’s ability to service the debt rather than relying solely on credit history as a disqualifying factor.