
Table of Contents
- Why 2026 Is the Best Time to Buy Used Compact Equipment
- How to Finance Used Compact Equipment Without Age Restrictions
- Financing for Older Equipment and Trucks: What Qualifies
- Auction Financing Pre Approvals: Bid With Confidence
- Step-by-Step: How to Finance Used Compact Equipment
- Common Mistakes That Slow Down Approval
- Frequently Asked Questions
Last Updated: September 22, 2026
Why 2026 Is the Best Time to Buy Used Compact Equipment
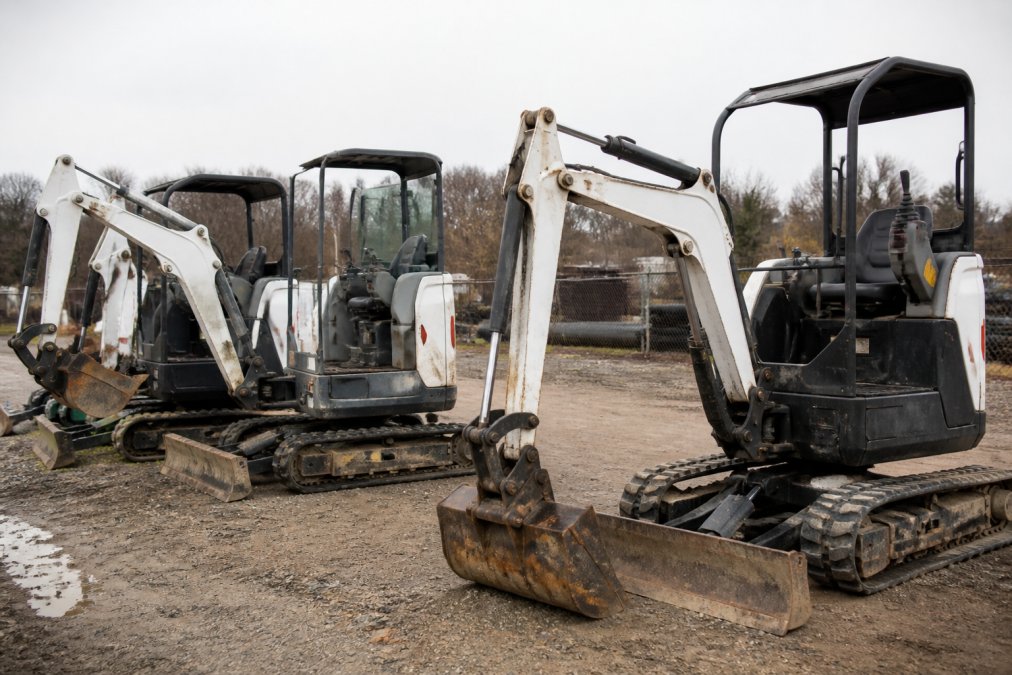
Late-season auctions and dealer trade-in cycles have pushed more used compact equipment onto the market than at any point in recent memory. For contractors who know how to finance used compact equipment without age restrictions, that means more supply, softer pricing, and lenders who no longer treat high-hour machines as automatic declines. This guide from Always Capital covers how that financing works.
- Rental fleets are rotating out compact excavators, skid steers, and mini loaders after standard service cycles.
- Dealer trade-ins from fall paving and grading work are landing on lots before winter.
- Auction houses are running larger consignment events, which spreads bidding pressure across more units.
U.S. Small Business Administration loan programs
How to Finance Used Compact Equipment Without Age Restrictions
Financing used compact equipment without age restrictions means approval is built on the machine’s condition, hours, and current market value rather than its model year. Always Capital finances equipment and trucks with no age or mileage restriction, so a 2008 skid steer and a 2024 mini excavator follow the same review path.
That is a shift from how most traditional lenders operate. Always Capital built its programs around the idea: if the machine runs, holds value, and has a clear title, it can be financed. Always Capital offers business financing for all credit types, and all applications are accepted.
What Lenders Look At Instead of Age
When age is off the table, underwriting shifts to five concrete inputs:
- Machine condition and hours. A unit with documented service records reads as lower risk than a low-hour machine with no paper trail.
- Current market value. Lenders compare the asking price against recent comparable sales for the same model and configuration.
- Collateral strength. The equipment itself secures the loan, so resale demand for that model matters as much as the buyer’s file.
- Business revenue and time in operation. A steady work history with repeat customers carries more weight than a single strong year.
- Credit profile. Always Capital works with all credit types, and all applications are accepted.
The loan-to-value ratio, meaning how much of the machine’s appraised value the lender covers, is the lever that moves the final structure. Always Capital offers 100% business financing options, removing the down payment barrier that stops many contractors from buying at auction. Always Capital also runs a soft credit pull only, so the application does not hurt your credit.
How Age Actually Affects the Deal (Even Without a Cutoff)
No age restriction does not mean age is invisible. It means age shows up as a value question instead of a yes-or-no question.
- 0-5 years old. Strong resale demand, deep comparable sales data, and the widest approval window.
- 6-10 years old. Still financeable, but the lender leans harder on service records and hour meter readings.
- 11-15 years old. Approval usually hinges on a third-party inspection and a clear title; expect the lender to weight the machine’s working life remaining.
- 15+ years old. Deals still close, but the file needs an appraisal, an inspection, and often a stronger business revenue picture to offset the thinner resale market.
A well-maintained 2012 mini excavator with 3,000 hours and full service logs can be a stronger file than a neglected 2019 unit with no records.
Why Compact Equipment Is Treated Differently Than Full-Size Iron
Compact equipment is the smaller class of construction machinery, typically under 12,000 pounds, including mini excavators, skid steers, compact track loaders, and small backhoes. These units hold value well, move fast when listed, and have a broad buyer pool of small contractors, landscapers, and rental yards.
U.S. Small Business Administration loan programs
Financing for Older Equipment and Trucks: What Qualifies
Older iron qualifies when the machine still has working life left and the paperwork backs it up. Always Capital finances used compact equipment, full-size machines, and commercial trucks regardless of age or mileage, including excavator financing, skid steer financing, backhoe financing, and dump truck financing.
- Compact excavators and mini excavators
- Skid steers and compact track loaders
- Backhoes and small dozers
- Wheel loaders and crawler equipment
- Dump trucks, daycabs, and box trucks
- Pavers, compactors, and forestry equipment
Inspection Requirements for High-Hour Machines
High-hour machines need proof, not promises. A third-party inspection report showing engine hours, hydraulic condition, undercarriage wear, and any prior repairs gives the lender something concrete to underwrite.
Most approvals move faster when the seller provides:
- A recent service history or maintenance log
- Photos of the machine from all four sides plus the hour meter
- A title search confirming no existing lien
- An independent equipment appraisal for units above a certain value
Auction Financing Pre Approvals: Bid With Confidence
Auction financing pre approvals let a buyer walk into a sale knowing the funding is already lined up. Always Capital issues pre-approvals before the auction date, so bidding is not limited by cash on hand. Always Capital offers auction financing pre approvals as a standing program, which is why contractors who buy at auction line up funding days before the gavel drops.
The process is straightforward:
- Apply with Always Capital before the auction.
- Get a pre-approval amount based on the equipment type.
- Bid up to that amount with confidence.
- Close the loan once the winning bid is confirmed.
Private Party vs. Dealer Purchase: Where Deals Actually Stall
Dealer purchases come with paperwork the lender already trusts: a standard invoice, a title in the dealer’s name, and a known chain of custody. Private party sales do not, which can lead to financing challenges. The machine may be great, but the file is only as strong as the paperwork behind it.
Purchase Type | Paperwork Risk | Typical Speed | What to Prepare |
|---|---|---|---|
Dealer purchase | Low | Fast | Standard invoice, dealer title |
Private party sale | Higher | Slower | Bill of sale, clear title, inspection report |
Auction purchase | Moderate | Fast with pre-approval | Winning bid confirmation, auction invoice |
- Title in the seller’s name. If the seller is flipping a machine they never titled, the lender cannot perfect a lien, and the deal stops until the title chain is cleaned up.
- No standard invoice. A handwritten bill of sale with no VIN, no hour meter reading, and no seller identification is not enough for most files. Ask for a written bill of sale that lists the make, model, year, serial number, hours, and both parties’ full legal names.
- No inspection. Private sellers rarely have service records, so an independent inspection becomes the substitute. Always Capital reviews both dealer and private party transactions, but the cleaner the paperwork, the faster the funding.
The Pre-Funding Inspection Step Most Buyers Skip
- A recent service history or maintenance log
- Photos of the machine from all four sides plus the hour meter
- A title search confirming no existing lien
- An independent equipment appraisal for units above a certain value
Budgeting for Immediate Repairs on Older Iron
Federal Trade Commission guidance on buying and selling used equipment
Step-by-Step: How to Finance Used Compact Equipment
Always Capital offers application-only approvals up to $500,000 with no financials required, plus 100% financing options up to $5 million for larger purchases. That range covers everything from a single mini excavator to a full fleet upgrade.
Common Mistakes That Slow Down Approval
The mistakes that cost the most time:
- Waiting until after the auction to apply. Pre-approval is what makes auction bidding possible.
- Leaving the maintenance history blank. Service records are the strongest signal of condition.
- Skipping the title search. An existing lien stops funding until it is cleared.
- Understating the machine’s hours. Lenders verify, and mismatches raise red flags.
- Applying with a hard credit pull elsewhere first. Multiple hard pulls in a short window complicate the file.
Occupational Safety and Health Administration guidance on heavy equipment operation
Frequently Asked Questions
Can you get financing for older heavy equipment?
Yes. Always Capital finances used compact equipment and commercial trucks with no age or mileage restrictions. Lenders evaluate the machine’s current condition, service history, and market value instead of its model year. Always Capital offers application-only approvals up to $500,000 with no financials required, and 100% financing options up to $5 million. Soft credit pulls only, so your credit score is not affected when you apply.
How quickly can I get approved for heavy equipment financing?
Always Capital provides same-day approvals within two to four hours. The process uses a soft credit pull, so it does not hurt your credit. You can get pre-approved for auction financing or dealer purchases before you bid. Always Capital accepts all credit types and works with businesses that have challenged credit or limited financial history.
What types of used commercial trucks can be financed?
Always Capital finances dump trucks, daycabs, box trucks, roll-off trucks, and other commercial vehicles with no age or mileage restrictions. Whether you are buying from a dealer, a private seller, or an auction, Always Capital offers pre-approvals so you can move fast. Financing for older equipment and trucks is a core part of what Always Capital does.
What are the benefits of buying used compact equipment for your business?
Used compact equipment costs less upfront, which preserves working capital for payroll and operations. Depreciation has already occurred, so you avoid the steepest value drop. Always Capital offers 100% financing on used equipment with no age restrictions, so you can acquire machines without a large down payment. Deferred payment plans of 30, 60, or 90 days help with cash flow.