
Table of Contents
- Why Caterpillar Equipment Is a Smart Investment for Your Business
- Heavy Equipment Loans: What to Expect in 2026
- Heavy Equipment Financing Pre-Approval: How to Get Started
- Excavator Financing for Your Next Project
- Dump Truck Financing to Keep Your Fleet Moving
- Why Always Capital Is the Best Choice for Caterpillar Equipment Financing
- Conclusion: Get Pre-Approved for Your Caterpillar Equipment Today
- Frequently Asked Questions
Last Updated: September 29, 2026
Why Caterpillar Equipment Is a Smart Investment for Your Business
Caterpillar equipment holds its value and keeps working long after other machines quit. That durability is why contractors, excavating companies, and fleet operators keep coming back to the yellow iron. This guide from Always Capital covers how to finance it, from heavy equipment loans to same-day approvals.
The numbers tell the story. According to Caterpillar’s 2025 annual report, the company generated $64.8 billion in revenue, a reminder of just how much of the world’s construction and mining work runs on Cat machines. Excavators, dozers, loaders, and articulated trucks built by Caterpillar show up on job sites in every state, from grading crews to mining operations.
Buying that equipment outright is rarely the smartest move for a growing business. Financing preserves working capital while the machine starts earning on day one.
Heavy Equipment Loans: What to Expect in 2026
Heavy equipment loans in 2026 favor speed and flexibility over paperwork. Lenders that still require weeks of documentation are losing ground to providers that approve in hours.
Here’s what a modern heavy equipment financing pre-approval process looks like:
- Application-only approvals for qualified borrowers
- Soft credit pulls that don’t affect your personal credit
- Terms from 24 to 84 months
- Deferred payment options of 30, 60, or 90 days
- Financing for older machines with no age or mileage restrictions
The last point matters more than most buyers realize.
Financing Need | Typical Structure | Best For |
|---|---|---|
New excavator or dozer | 24-84 month terms | Contractors adding capacity |
Used equipment, any age | No age restrictions | Budget-conscious fleets |
Dump truck or daycab | Same-day approval | Hauling and logistics |
Working capital + equipment | Combined facility | Growing operations |
Heavy Equipment Financing Pre-Approval: How to Get Started
Heavy equipment financing pre-approval is the step that tells you what you can buy before you walk the auction lot. It takes minutes to start and removes the guesswork from bidding.
The process is straightforward:
FIND OUT HOW MUCH YOUR BUSINESS CAN BORROW TODAY ! →
- Submit a short application with basic business details
- Receive a soft-pull decision, usually within two to four hours
- Get your pre-approved amount and terms in writing
- Shop dealers, auctions, or private sellers with confidence
- Finalize once you’ve chosen your machine
Excavator Financing for Your Next Project
Excavator financing covers everything from a compact mini excavator for residential work to a 90-ton crawler for mass excavation. The right structure depends on how the machine will earn, and on which Caterpillar class you actually need.
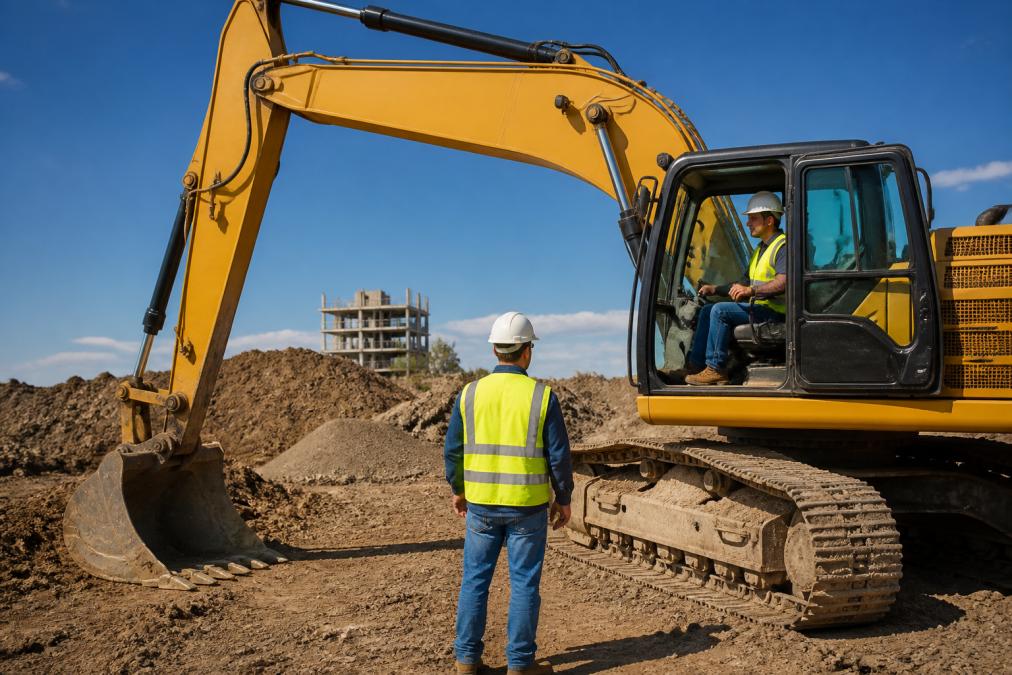
- Mini excavators (roughly 1 to 10 metric tons). Machines like the 301.7 CR through the 310 fit residential footings, utility trenching, and landscaping. They finance quickly, often through simplified approval, and they are the easiest class to bundle with a trailer and attachment package.
- Small and mid-size excavators (roughly 11 to 35 metric tons). The 320, 330, and 335 classes are the workhorses of general contracting, site prep, and road work. These units typically carry the longest duty cycles and the strongest resale position.
- Large crawler excavators (roughly 36 metric tons and up). The 349, 374, and 395 classes handle mass excavation, quarry loading, and deep sewer work. These deals usually need more documentation because the machine is a dedicated production asset.
Three factors shape an excavator deal:
- Machine class. Mini excavators finance quickly and often qualify for simplified approval. Larger crawler units may need more documentation.
- Attachment package. Breakers, thumbs, grapples, and couplers can be bundled into the same agreement, so the machine arrives job-ready instead of requiring a second purchase later.
- Use plan. Machines running daily on contract work justify shorter terms than occasional-use units.
The lifecycle angle most buyers miss
A financing decision is really an ownership-cost decision. The purchase figure is only the entry point; the real number is what the machine costs you per hour of production across its whole service life. Three levers drive that:
- Undercarriage wear. On a crawler excavator, the undercarriage is the single largest recurring wear item. Track chains, rollers, idlers, and sprockets wear as a set, and operating in abrasive soil or on rock shortens that interval sharply. A machine that spent its life in sand behaves very differently from one that worked in shot rock.
- Hydraulic system health. Contamination is the quiet killer. Regular fluid sampling and filter discipline are what separate a 12,000-hour machine from a 6,000-hour machine of the same model year.
- Service network and parts availability. Caterpillar’s dealer network is one of the deepest in the industry, which shortens downtime when something fails. That matters directly to your cost per hour, because a machine waiting on a part is still a machine you’re paying for.
Dump Truck Financing to Keep Your Fleet Moving
Dump truck financing keeps hauling revenue flowing when a truck goes down or a new contract demands more capacity. Fleet owners know that an idle truck is a losing truck.
Financing works for the full range of commercial trucks:
- Dump trucks, including standard, roll-off, and transfer units. Roll-off and transfer configurations often work harder per mile than a standard dump, which affects how you want to structure the term.
- Daycabs for regional and local hauling. A daycab that runs a fixed local route is one of the most predictable assets in a fleet, which makes it one of the easiest to finance.
- Box trucks for delivery and service work. These units tend to have longer, gentler duty cycles than construction trucks, so they hold value differently.
- Tractors and specialty vehicles, including units built for specific hauling contracts.
Configuration drives the deal
Three configuration questions shape how a truck finances:
- Body and bed type. A dump body, a roll-off frame, and a transfer trailer are different assets with different wear patterns. Lenders who understand vocational trucks look at the whole unit, not just the chassis.
- Axle and suspension setup. Tandem versus tri-axle, and the suspension package underneath, determine what the truck can legally haul, and therefore what it can earn.
- Duty cycle. A truck running 60,000 miles a year on pavement is a different risk profile than one running 20,000 miles a year in and out of a pit.
Age and mileage are not deal-breakers. Always Capital finances older trucks with no age or mileage restrictions, which matters when a well-maintained 2015 model is still the most cost-effective option on the lot. A truck with a documented service history and a fresh DOT inspection is often a better asset than a newer unit with unknown maintenance.
The lifecycle angle most buyers miss
On a vocational truck, the purchase figure is only the entry point. The number that actually matters is cost per loaded mile across the truck’s service life. Three levers drive it:
FIND OUT HOW MUCH YOUR BUSINESS CAN BORROW TODAY ! →
- Preventive maintenance discipline. Oil analysis, brake adjustment, and tire rotation schedules are what separate a 500,000-mile truck from a 250,000-mile truck of the same model year.
- Body and hydraulic wear. On a dump truck, the hoist cylinder, pump, and bed floor take a beating. A truck that hauled rock behaves very differently from one that hauled mulch.
- Parts and service access. A truck that can be serviced locally spends less time down, and downtime is the most expensive thing in a fleet.
Why Always Capital Is the Best Choice for Caterpillar Equipment Financing
Always Capital is the fastest path to a Caterpillar purchase for businesses that need equipment now, not next month. The company built its entire model around speed and access.
What sets it apart:
- Two-hour approvals. Decisions arrive in two to four hours, not days.
- 100% financing. Qualified borrowers can finance the full equipment cost.
- All credit types accepted. Past credit issues don’t automatically disqualify an application.
- Application-only approvals up to $500,000. No financials required for many deals.
- Soft credit pulls only. Checking your options never hurts your credit.
- Support for young businesses. Companies under two years old can qualify.
Conclusion: Get Pre-Approved for Your Caterpillar Equipment Today
Equipment doesn’t wait, and neither should financing. Every day a machine sits unbought is a day it isn’t earning.
Frequently Asked Questions
How can I get fast approval for heavy equipment financing?
Always Capital offers same-day approvals within 2-4 hours. Apply online with a soft credit pull that does not affect your credit score. With application-only approvals up to $500,000 and no financials required, you can get pre-approved quickly. Visit alwayscapital.com/apply-now to start your application and get the equipment you need without delays.
Does equipment financing require a hard credit pull?
Always Capital uses only soft credit pulls during the application process, so your credit score is not impacted. This allows you to explore financing options without worry. All credit types are accepted, making it easier for businesses with challenged credit to get approved. Apply now at alwayscapital.com/apply-now to see your options.
Can I finance older heavy equipment models?
Yes, Always Capital offers financing for older equipment and trucks with no age or mileage restrictions. Whether you need a used excavator, dump truck, or dozer, you can secure funding. This flexibility helps businesses acquire reliable equipment without the high cost of new models. Get pre-approved at alwayscapital.com/apply-now.
What types of heavy equipment can be financed for my business?
Always Capital finances a wide range of heavy equipment, including excavators, backhoes, skid steers, loaders, dozers, tractors, pavers, dump trucks, daycabs, and box trucks. Whether you need construction machinery for grading, paving, or hauling, we have financing solutions. Apply now at alwayscapital.com/apply-now to get started.